Orders, stops and the price you actually get
Learn which part of an order you control, which part the market controls, and why a stop is not insurance.
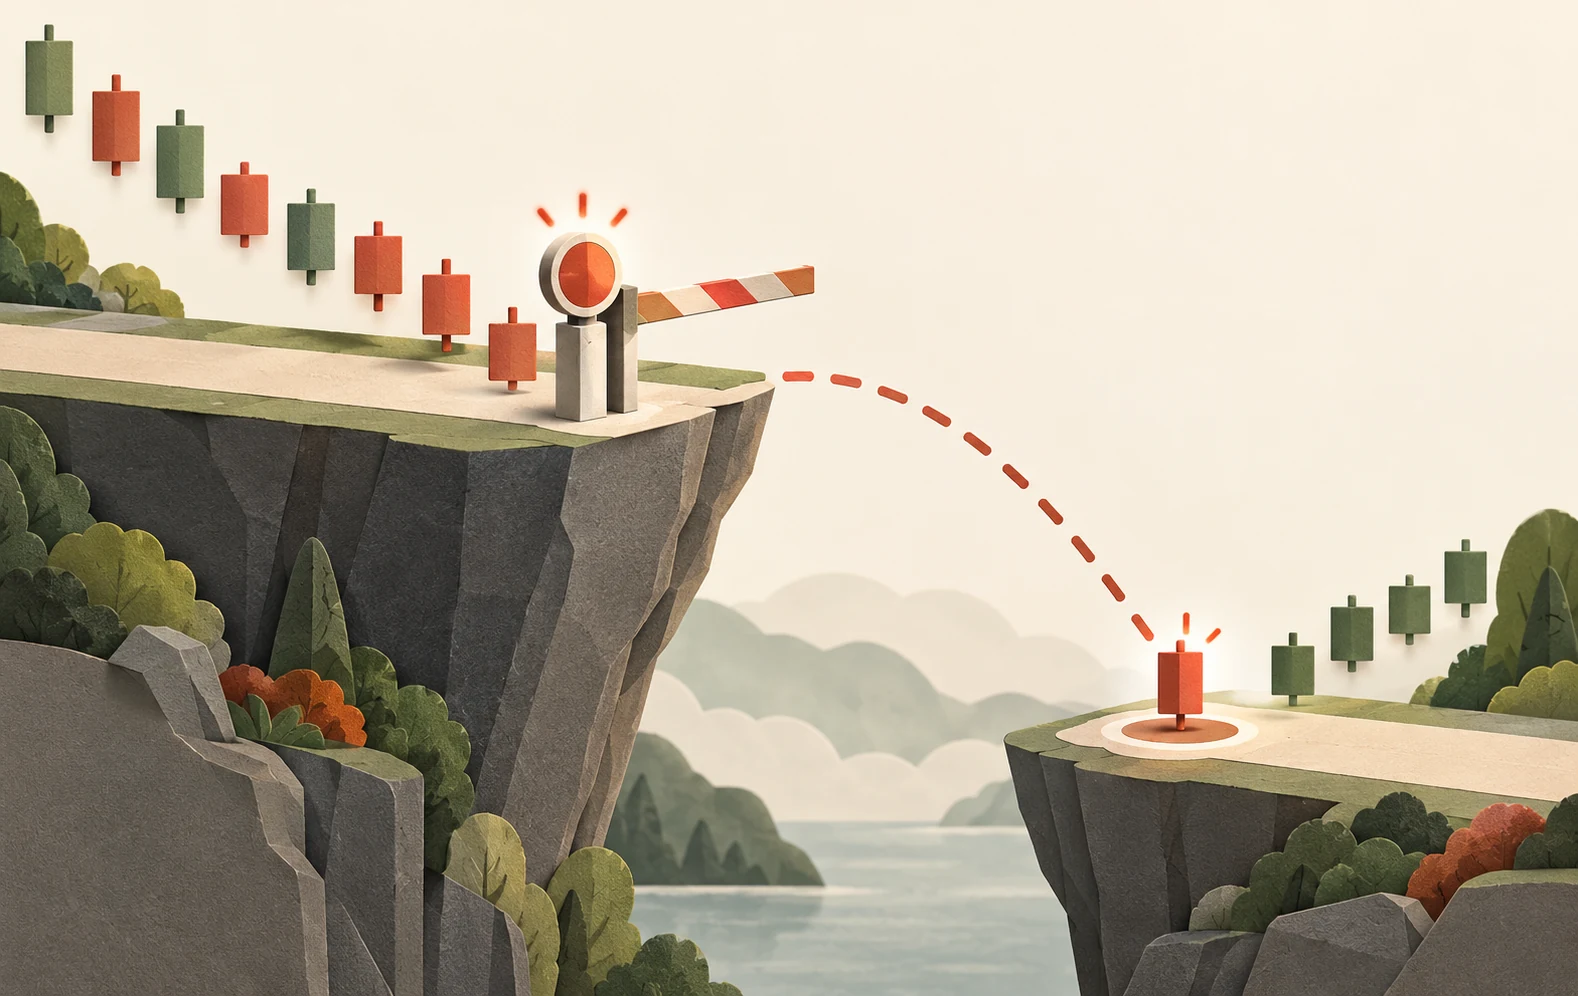
An instruction is not a result
An order describes what a broker or venue should try to do under specified conditions. The resulting execution depends on available counterparties, trading hours, market rules and operational conditions. A chart shows past transactions; it is not an offer to trade any quantity at the most recent price. That distinction becomes visible when prices move quickly or available size is small.
A market order prioritizes execution rather than a particular price. A limit order specifies the worst acceptable price but can remain unfilled. For a purchase, the limit is the maximum price; for a sale, it is the minimum. Partial fills can leave a smaller position than intended, and the rest of an order may remain active.
Available quantity matters as much as the best displayed price. A quote offering 100 shares at one price does not promise that 1,000 shares can be bought there. A larger market order may trade at several price levels, and its average fill can differ from the first fill. A limit order may instead consume the quantity available within its limit and leave the remainder waiting, depending on its time-in-force instructions and the venue’s rules.
Understand what the trigger actually triggers
A conventional stop order becomes a market order when its trigger condition is met. It is therefore exposed to slippage after activation. A stop-limit order instead becomes a limit order, preserving the stated price boundary while introducing the possibility of no exit. Neither order solves every risk. Different brokers may use different trigger references, so check whether activation depends on trades, bids, asks or another specified price.
Orders also have lifetimes. A day order may expire at the end of the relevant session, while a longer-lived order remains until its specified expiry or cancellation, subject to broker rules. Extended-hours eligibility and corporate-action treatment can differ. An unattended order is still an instruction with potential consequences, even when the original trading idea has been forgotten.
Walk through an overnight gap
Consider a hypothetical share bought at $50 with a sell stop at $48. After unexpected news, the next available buying interest appears around $44.50. An activated stop may fill there or at another available price. The intended $2 loss per share has become $5.50 before costs. This is not necessarily a malfunction; the missing prices were never available for execution.
A stop-limit with a $48 trigger and a $47.80 limit could remain unfilled in the same scenario. Its limit protects against accepting $44.50, but the investor still owns the falling asset. Price certainty and execution certainty compete with each other. It is misleading to describe one order type as universally safer without specifying which risk matters.
Reconcile the order after submission
Record the order identifier, side, quantity, limit or trigger, time in force and current status. Then distinguish submitted, accepted, partially filled, filled, rejected and canceled. A cancellation request is not proof that a trade did not execute; an execution may occur before the cancellation becomes effective. Reconcile positions and cash rather than relying only on an on-screen message.
In a simulation, deliberately test a rejected order and a partial fill. A realistic plan specifies what happens if the entry fills but its related exit does not, or if a connection drops. Platform features such as linked orders can help coordinate instructions, but their exact behavior is product-specific. Operational understanding belongs alongside price analysis, not after it.
Check whether the market is actually open for the instruction you intend to use. A price feed may continue displaying indicative prices while a particular order type is unavailable. An exchange halt or broker restriction can also prevent execution. These possibilities belong in the exercise notes because an exit plan that assumes uninterrupted access has left an important condition unstated.
Follow the quantity from instruction to position
Suppose a hypothetical purchase of 250 shares fills 100 at $50.02 and 150 at $50.05. Total purchase value is $12,509.50, and the quantity-weighted average price is $50.038 before fees. The average is not the midpoint of the two quoted prices because the quantities differ. Relative to buying all 250 at the first $50.02 price, the extra price cost is $4.50. This example assumes those fills were available; a real order book can change while an order is being processed.
Now consider a 100-share limit order. Forty shares fill, a cancellation is requested, and another ten fill before cancellation takes effect. If the final canceled remainder is 50 shares, the actual position is 50 shares—not zero and not the original 100. A record that labels the whole order “canceled” without showing cumulative fills is incomplete. The account’s position and trade confirmations are the quantities that subsequent instructions must reconcile.
Linked exits need the same attention. If a target and a stop are both intended to close an existing long position, an execution of one should not leave an unrelated live sell order that can open a short position later. Some platforms manage this through linked-order functionality, but cancellation timing, partial fills and broker implementation matter. In a paper exercise, explicitly test what happens when only part of the position exits or when both trigger conditions appear during a fast move.
A missing response creates an uncertain state, not evidence that an order failed. Re-submitting an entry after a connection interruption can create duplicate exposure if the first instruction was accepted. The operational question is therefore whether the original order exists and what has already filled. Build the simulation around order identifiers, acknowledgments and reconciled quantities rather than assuming that a second click is always a harmless retry.