Implementation shortfall: account for the decision you could not fill
Measure execution against a defined decision price, including the cost of unfinished orders.
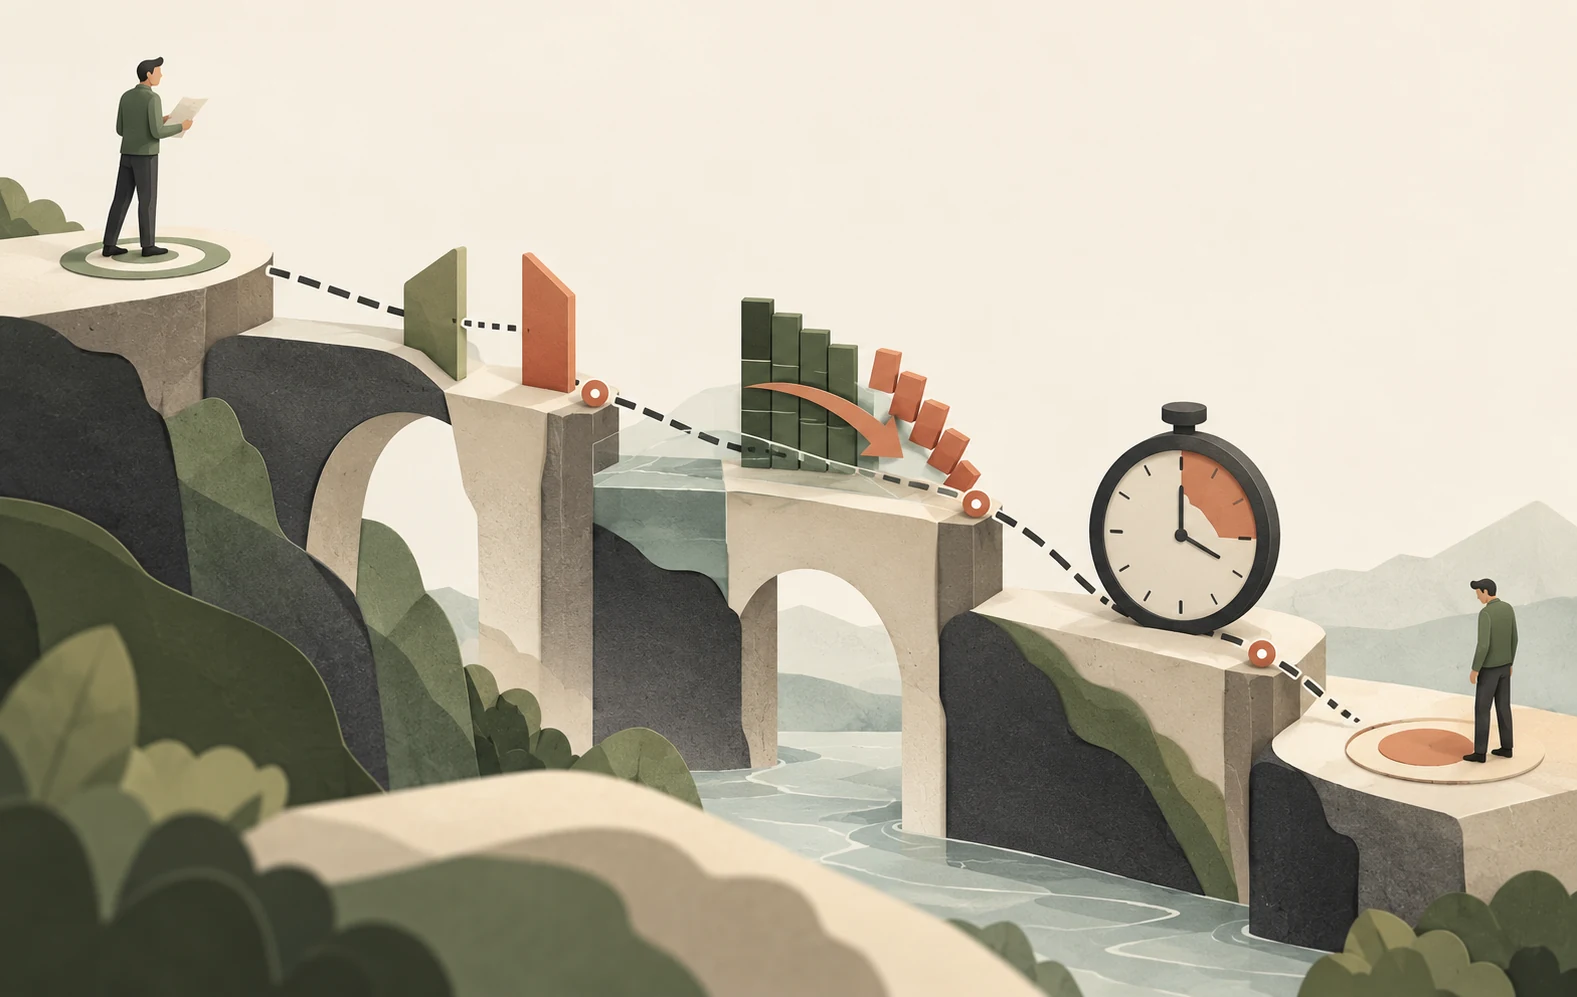
Choose a benchmark before judging a fill
An execution price is meaningful only relative to a benchmark and an objective. A trade can beat the day's average price while performing badly relative to the price available when the decision was made. Conversely, an urgent order may pay a higher price yet reduce the risk of missing a rapidly expiring opportunity.
Implementation shortfall compares the value of an intended paper decision with what was actually implemented, including explicit costs and, under the chosen convention, unfilled exposure. Define the decision timestamp, reference price, order size and evaluation endpoint in advance. Selecting whichever benchmark makes the execution look best destroys the measure's diagnostic value.
Separate delay, trading cost and missed exposure
The price may move between the investment decision and the arrival of the order at the market. It may then move again during execution. Fees add another component. Unfilled shares create an opportunity cost or benefit depending on what happens by the evaluation time. For a buy order, rising prices generally make these differences costly; for a sell order, the signs reverse.
These categories are accounting descriptions, not perfect causal attribution. A price rise during execution may reflect the order's own impact, public news or both. The calculation can establish that implementation differed from the decision benchmark without proving which participant or mechanism caused every cent of the difference.
Treat unfilled orders symmetrically
Ignoring unsuccessful limit orders creates a flattering record of passive execution. Filled orders may look cheap while the opportunities that ran away disappear from the dataset. Include every eligible decision, its requested quantity, cancellations and any remaining quantity at the predetermined endpoint.
Opportunity cost can be negative. If an unfilled buy order is followed by a price decline, the unfilled portion avoided a loss relative to immediate purchase. Do not count only the painful misses or only the fortunate ones. Consistent measurement across all decisions matters more than choosing a convention that produces a positive-looking average.
Keep the original parent order identifiable when it is split into smaller child orders. Ten fills belong to one intended decision, not ten independent successful decisions. If part of the order is canceled because the investment view changes, record the cancellation time and reason rather than rewriting the original requested quantity. A revised intention can start a new measurement episode, but the boundary must be defined consistently or missed trades will vanish through bookkeeping.
Normalize without hiding the economic size
Report costs in currency and basis points relative to a clearly defined notional amount. One basis point is 0.01%, so a 10-basis-point cost on $100,000 is $100. A small average in basis points can still be economically material for a high-turnover process, while a large percentage on a tiny order may have little portfolio impact.
Compare like with like: urgency, order size relative to market activity, volatility, time of day and venue conditions. A broker handling difficult orders should not be judged solely against easy orders elsewhere. Preserve the raw observations as well as summaries so unusual fills, stale timestamps and currency-conversion errors can be investigated.
Use measurement to improve the process
Execution analysis should identify controllable weaknesses: unnecessary decision delays, order sizes that exceed available liquidity or a mismatch between signal horizon and execution schedule. It should not encourage mechanically slow trading when the information decays quickly, nor mechanically aggressive trading when patience has value.
Evaluate proposed changes over a meaningful sample and include adverse conditions. A change that saves spread but greatly increases missed exposure may not improve total implementation. The relevant comparison is the completed investment process, not a single attractive component. Execution quality also includes operational reliability and appropriate handling of errors, which price statistics alone cannot certify.
Build a shortfall calculation that reconciles
For a buy decision, let Q be the intended quantity, q the filled quantity, Pd the decision price, Pf the quantity-weighted average fill price, and Pe the price at the predetermined endpoint. One simple currency convention is q(Pf − Pd) + (Q − q)(Pe − Pd) + explicit fees. It compares immediate ownership of all Q units at the decision price with actual fills and the remaining unfilled exposure. The endpoint is a valuation convention, not an assumption that the unfilled order actually traded there.
The filled component can be split further without changing the total. If Pa is the arrival price, then q(Pf − Pd) equals q(Pa − Pd) + q(Pf − Pa). In the existing example, suppose the 600 filled shares arrive when the price is $20.02 and fill at $20.05, after a $20.00 decision. Delay accounts for $12 and the arrival-to-fill difference for $18. Add the $80 unfilled component and $6 fees to recover the same $116 shortfall. Adding the unsplit $30 again would double-count it.
For a sale, a lower price is adverse, so reverse the signs of the price differences while retaining positive fees. The analogous sale formula is q(Pd − Pf) + (Q − q)(Pd − Pe) + fees. This makes a sale below the decision price a positive cost, while a higher sale price is a negative cost. Fixing the convention first prevents a dashboard from treating favorable and unfavorable outcomes inconsistently across trade directions.
Aggregation needs equal care. A $10 shortfall on a $1,000 order is 100 basis points; a $100 shortfall on a $100,000 order is 10 basis points. Their simple average is 55 basis points, but combined shortfall is $110 on $101,000, or about 10.89 basis points. The former describes the average order’s percentage cost; the latter describes cost per dollar of intended exposure. Report the weighting rule, and convert currencies consistently before adding monetary amounts.